China’s Debt Reckoning
China’s interest bill is crowding out its budget just as Beijing needs room to stimulate a slowing economy.
November 20, 2026

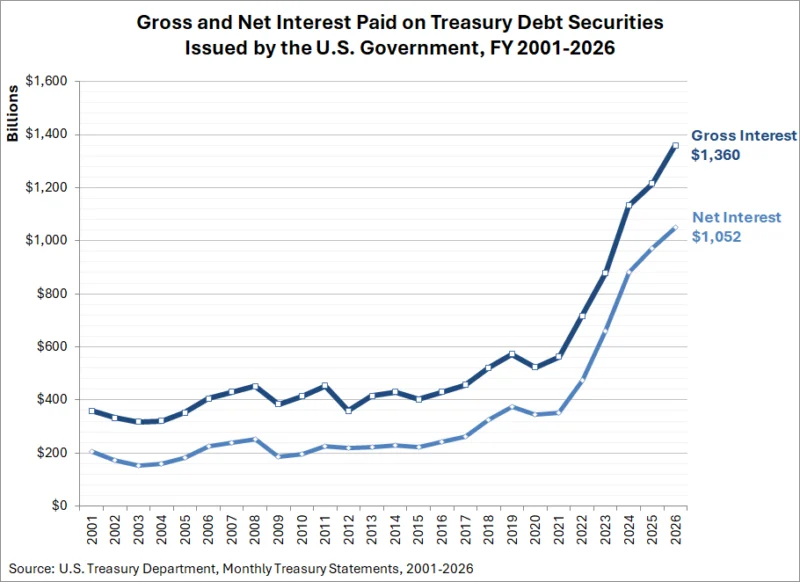
Borrowing to fund a government’s excessive spending can cost more than just the interest it has to pay.
That lesson is being relearned in more countries than just the United States. Fortune’s Jason Ma reports on how the skyrocketing interest costs on money China borrowed years ago limit its ability to stimulate its economy now, when it needs to.
The world is flooded with debt, but while the U.S. and Europe have caused angst on global markets lately, China’s fiscal situation isn’t looking so great either.
In fact, China’s debt has shot up so much in recent years that interest payments on all its borrowing are commanding a bigger share of public spending.
Debt-servicing payments will account for 19.2% of the central government’s general public budget this year, up from 12% in 2014, according to new Conference Board estimates cited by the Financial Times.
That’s a big increase in a short time, so big that it is crowding out other spending China’s government needs to undo the damage from its earlier debt-fueled spending binges.
From 2008 through 2021, China’s government borrowed trillions to stimulate its economy by boosting politicians’ favored industries whenever growth threatened to fall short of their targets.
But because its leaders have chosen its economy’s winners and losers this way, China now has to cope with how wasteful much of that borrowing-fueled spending has been. Its repeated misallocation of stimulus has sapped its economic potential. Jason Ma describes the worsening outcomes of China’s politician-managed economic experiment:
China’s GDP has been decelerating and is on pace to undercut its annual target of 4.5% to 5%. And while export-facing sectors are growing at a fast clip, trade partners are putting up barriers; Chinese consumers remain reluctant to spend; investment is weak; the property sector is still digging out from an epic crash; and Chinese stocks have been anemic.
Beijing has also steered state banks to provide financing to priority industries like electric vehicles, robotics, artificial intelligence, and renewable energy.
But under pressure to lend, many loans went to questionable borrowers. Business debt has doubled since 2019, while revenues are only 30% higher. Creditors continue to roll over loans to keep struggling firms afloat, even as nearly a third of them are losing money.
China’s state-led growth model now looks like it’s running out of steam, and the rapidly expanding mountain of debt is a warning sign as local governments often seek to boost favored industries with low-cost loans.
China’s politician-led growth model works a lot like the double-down strategy in gambling, in which a gambler on a losing streak doubles the bet after every loss to try to win back all the lost money and come out ahead.
Worse, they’re borrowing to fund their bets, all while they continue wagering too much on high-risk propositions chosen by politicians trying to stack the deck in their favor. The scheme is proving to be a fast way to dig a fiscal hole so deep they may never climb out of it.